A technician might have worked eight hours at client sites but only see five of them on the month's invoices. The other three hours are not necessarily "lost" in accounting terms. They may have been used to prepare equipment, travel, correct an installation, call a supplier, or respond to a client. The problem begins when no one knows which of these hours should be billed, absorbed, or better organized. A billable time study is specifically designed to bring these discrepancies to light.
For a service-based SME, time is often the primary raw material. If hours do not follow the work order through to the invoice, the margin is decided in text messages, timesheets filled out on Fridays, and end-of-month recollections. This is not a matter of monitoring teams. It is a matter of seeing the work actually performed so it can be delivered, billed, and improved.
A billable time study starts with the right discrepancies
The goal is not to bill every minute of the day. A company must maintain non-billable time: internal meetings, training, vehicle maintenance, health and safety, general preparation, or business development. Instead, the study helps distinguish what is normal from what is slipping out of control.
You must separate four realities that are often conflated. Available time corresponds to paid hours. Worked time is what the team actually did. Billable time is the portion that can be charged to the client according to the agreement, mandate, or rate. Finally, billed time is what has actually been converted into an invoice line item.
Between each of these stages, there can be a leak. An hour worked may never be recorded. A recorded hour may be classified in the wrong category. An eligible hour may remain pending because the work order is not validated. A validated hour may wait three weeks before being billed. These situations do not have the same cause or the same fix.
Take a technical maintenance company. Its team accumulates 640 hours in a month. After removing meetings, training, and planned administration, 470 hours should be associated with client interventions. However, only 410 hours appear on invoices. The 60-hour gap deserves to be studied before concluding that employees lack productivity. Perhaps travel is included in the flat rate. Perhaps urgent service calls are not documented. Perhaps work orders closed in the field are waiting for office approval.
Tracking time in context, not in an isolated box
A timesheet alone rarely answers all questions. It indicates that a person worked seven hours, but it does not prove for which client, on which equipment, at what stage, or with what expenses. The office must then ask for details, search through emails, call the technician, or guess based on a calendar.
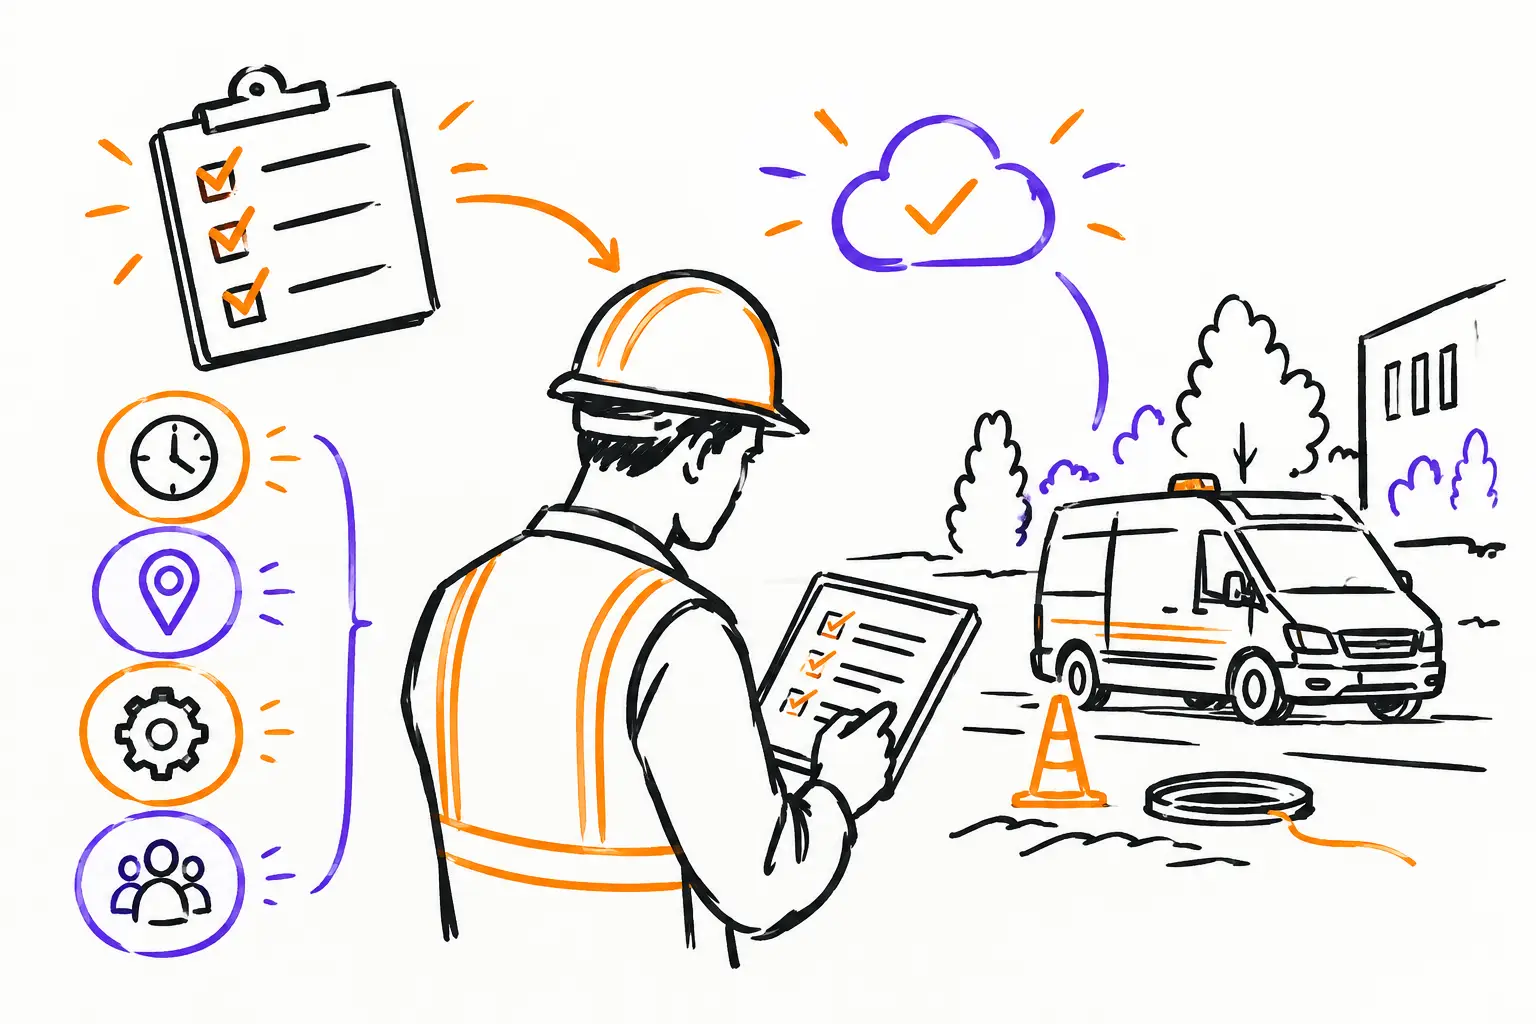
Time becomes useful when it is linked to the document that carries the work. Depending on the company, this document can be a work order, a ticket, a mandate, or a project. The field team opens the file, consults the procedure, enters their hours, adds a photo if necessary, and has the intervention validated. The time then arrives at the office with its client, status, description, and the elements necessary for billing.
This workflow also reduces unnecessary discussions. If an intervention exceeded the estimate, the manager can see if the discrepancy comes from unexpected travel, a missing part, a rework, or a request added by the client. They do not judge a line of hours without knowing the field reality.
This is the benefit of a document-centered approach: your methods remain visible. An excavation company does not break down its time like a production agency, and a specialized workshop does not bill like a property manager. Categories, validations, and billing rules must follow your reality, not force you into a generic workflow.
How to conduct a useful billable time study
Start with a representative period of four to eight weeks. A single very quiet month, a vacation period, or an exceptional project can skew the analysis. Also, choose a specific team, type of intervention, or service line if your organization is large. It is better to get a clear answer on one sector than to produce a report that is impossible to use.
1. Define what is billable before measuring
The first discussion must bring together operations and administration. Which hours are included in the price? Is travel billable? Should reworks caused by internal errors be identified? At what threshold does an additional visit require client approval?
Write these rules simply. For example, a service call might include 30 minutes of travel, then bill for kilometers beyond a given territory. A fixed-price project might track hours to measure profitability, even if they will not be billed separately. Without these rules, two people might handle the same situation differently and create a discrepancy that seems mysterious in reports.
2. Compare planned, recorded, and billed
For each work document, observe three figures: the time planned or sold, the time recorded by the team, and the time retained for the invoice. This comparison tells much more than the total payroll hours.
If recorded time often exceeds planned time, your estimates, procedures, or prices may need to be reviewed. If recorded time is low, but teams confirm they worked, the problem is likely mobile entry or the discipline of closing files. If time is recorded and validated, but slow to be billed, the bottleneck is between operations and the office.
3. Read the statuses that block money
Statuses must allow for action. "In progress," "to be validated," "ready to bill," and "billed" provide a clear view of files. A status that is too vague, like "completed," often hides an important question: completed in the field, completed for the client, or completed for accounting?
A report of completed but unbilled work orders is often more profitable than a large dashboard filled with indicators. It gives the administrative manager a concrete list to process. The manager can then see why each file is blocked: missing signature, pending photos, rate to be confirmed, material not entered, or client approval required.
4. Examine exceptions, not just averages
An overall billable time rate of 75% can be very healthy in one company and worrying in another. Everything depends on the share of internal work, the pricing model, the season, and the nature of the contracts. The average becomes useful when compared by team, mandate type, client, or intervention category.
Look for cases that stand out. Does a client request many more non-billed calls? Does a type of work often lead to a second visit? Does a team always forget to close their files on Fridays? These exceptions show where to change a rule, train a person, or adjust a quote.
Transforming results into concrete actions
A study only has value if it changes the next work cycle. If travel is never recorded, add it as a simple activity in the work order rather than asking employees to calculate it elsewhere. If hours are waiting for validation, give the project manager a notification and a clear deadline. If overruns are frequent, ask for approval from the field before continuing work outside the mandate.
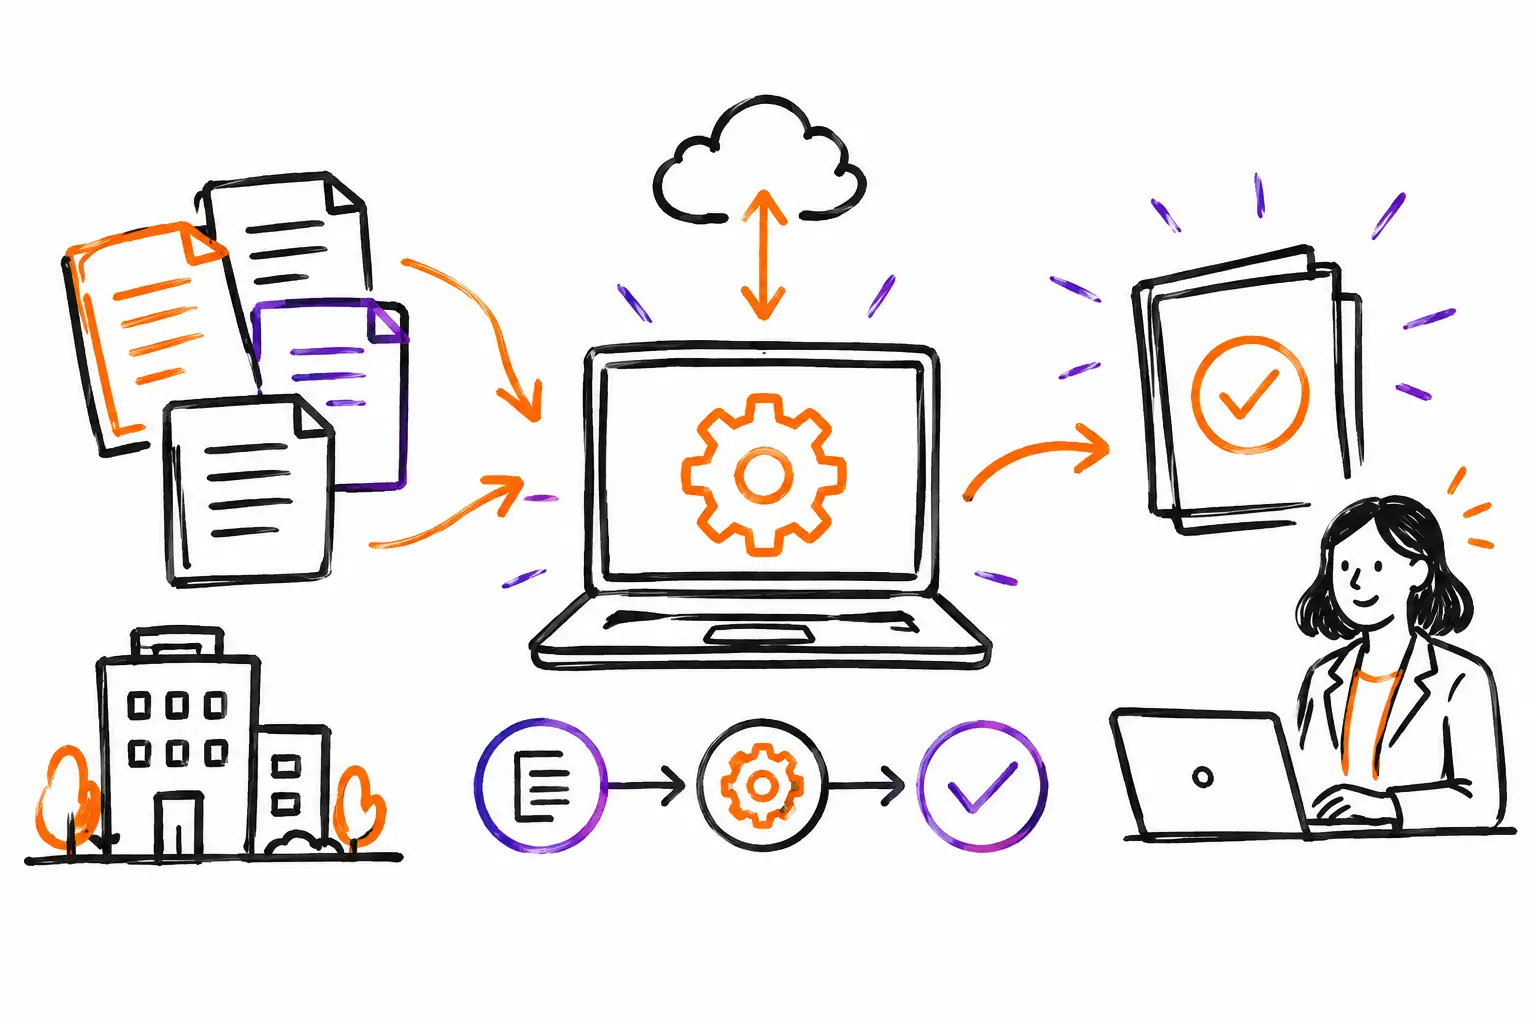
The right process also links data already collected. An accepted quote becomes a work document. Hours, parts, expenses, and validations are added during execution. When the file is ready, the invoice reflects what was actually done. With Sequentia, this continuity avoids re-entering hours into one tool, verifying them in another, and rebuilding the invoice by hand.
Do not try to correct all discrepancies at once. Choose a priority indicator, such as the number of completed work orders not billed for more than five days. Measure it every week. Once the delay is stabilized, tackle another source of loss, for example, service calls without travel time.
Indicators to keep an eye on
The billable time rate is useful, but it is not enough. Also track the delay between the end of the work and the issuance of the invoice. An hour perfectly recorded that waits 30 days weighs on cash flow. Look at the value of completed unbilled work, hours corrected after the fact, and discrepancies between estimated and actual time.
These indicators should trigger an operational conversation, not become a tool for blame. When teams understand that their entry avoids calls from the office, protects the price of the work, and accelerates the invoice, adoption is more sustainable. The field does not need another report: it needs a simple file to complete while the intervention is still fresh.
A good billable time study does not look for culprits. It gives your company an honest view of the work delivered, what can be monetized, and what deserves to be better managed. Start with one type of work order and a few weeks of data. The most costly discrepancies often appear well before the end of the report.